Qualified applicants, delivered the way your systems already work.
NeerCred pre-screens and structures every personal-loan applicant before they reach you — then delivers them through whichever integration fits your stack.
Most aggregator traffic costs underwriting time before it costs money: duplicate applicants, incomplete KYC, and a manual review queue that grows faster than conversion. NeerCred's job is to remove that step, not add another feed for your team to manage.
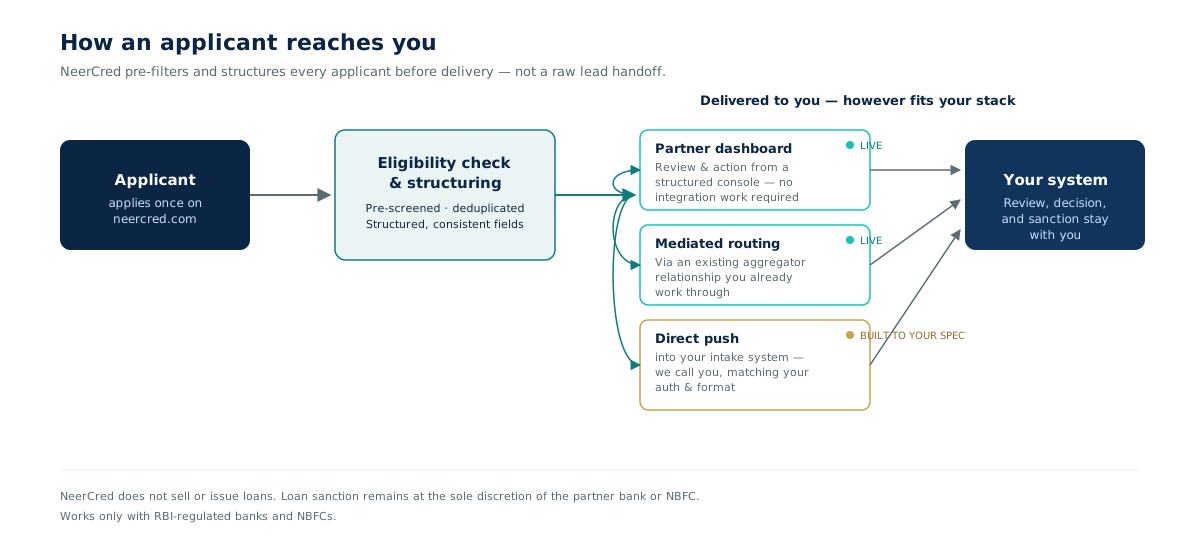
How an applicant reaches you
Three real delivery methods — not a single rigid pipe.
Partner dashboard
Live today
Review and action every matched applicant from a structured console — no integration work required to get started.
Mediated routing
Live today
Already work through an aggregator relationship? NeerCred plugs into that existing channel — same structured data, no new integration surface.
Direct push
Built to your stack
NeerCred calls into your existing intake system directly, matching the authentication and format it already expects. You don't integrate into us — we integrate into you.
Applicants are matched against your basic criteria in real time, before they ever reach your queue — not after.
Structured, not raw
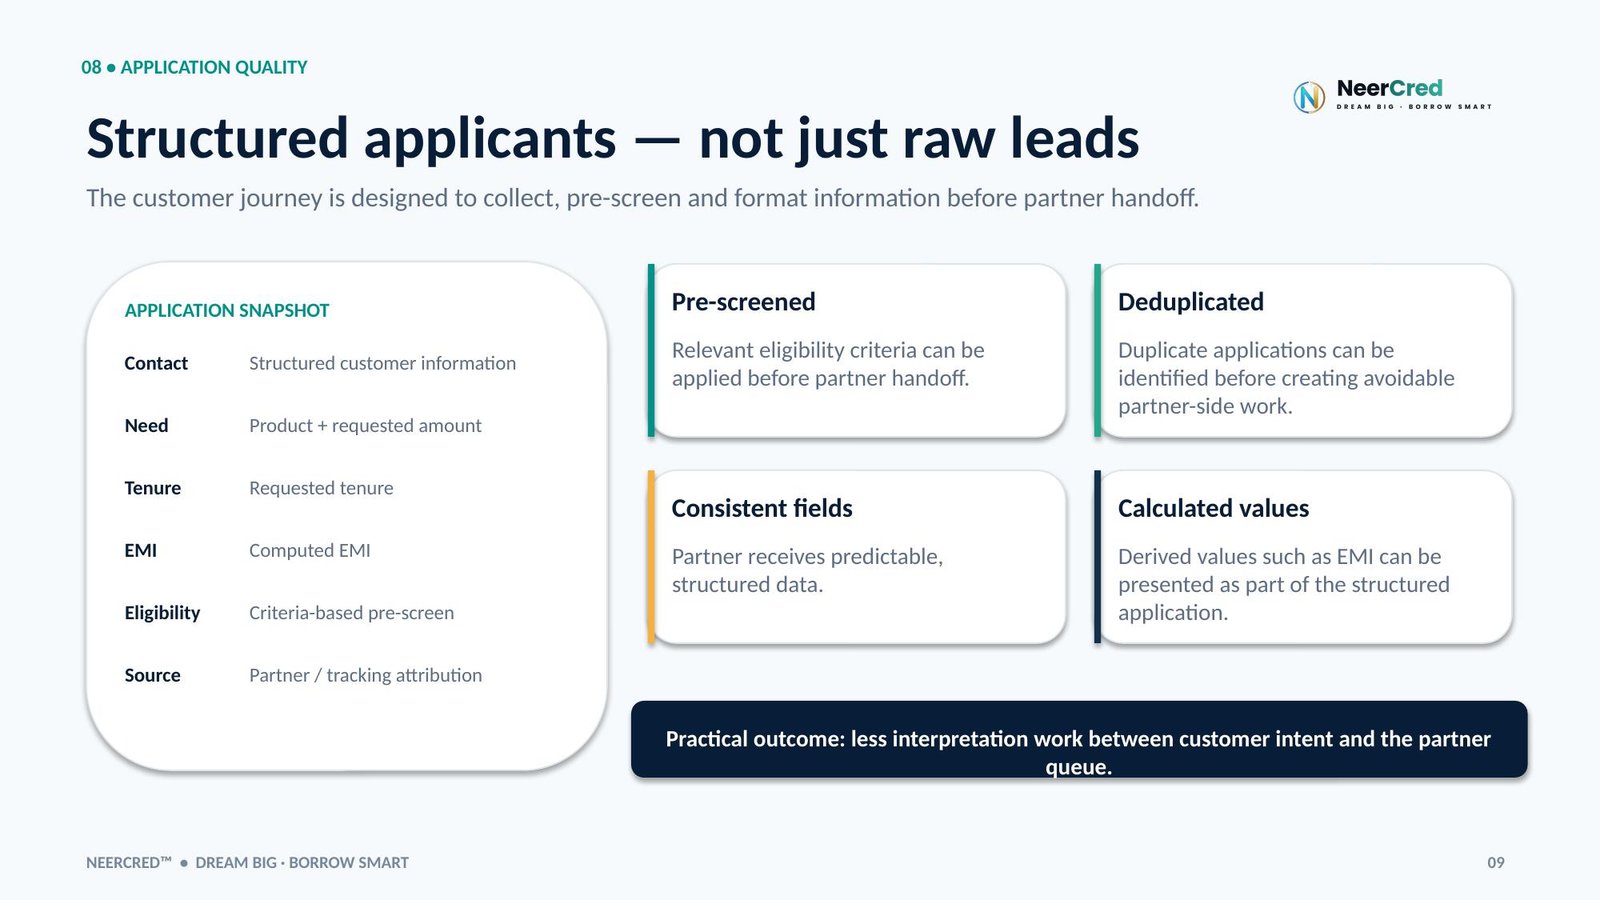
Verified contact details, computed EMI, requested amount and tenure arrive in a consistent shape instead of a freeform form your team has to parse.
Deduplicated
No repeat applicants across channels.
Built for integration, not a landing-page promise
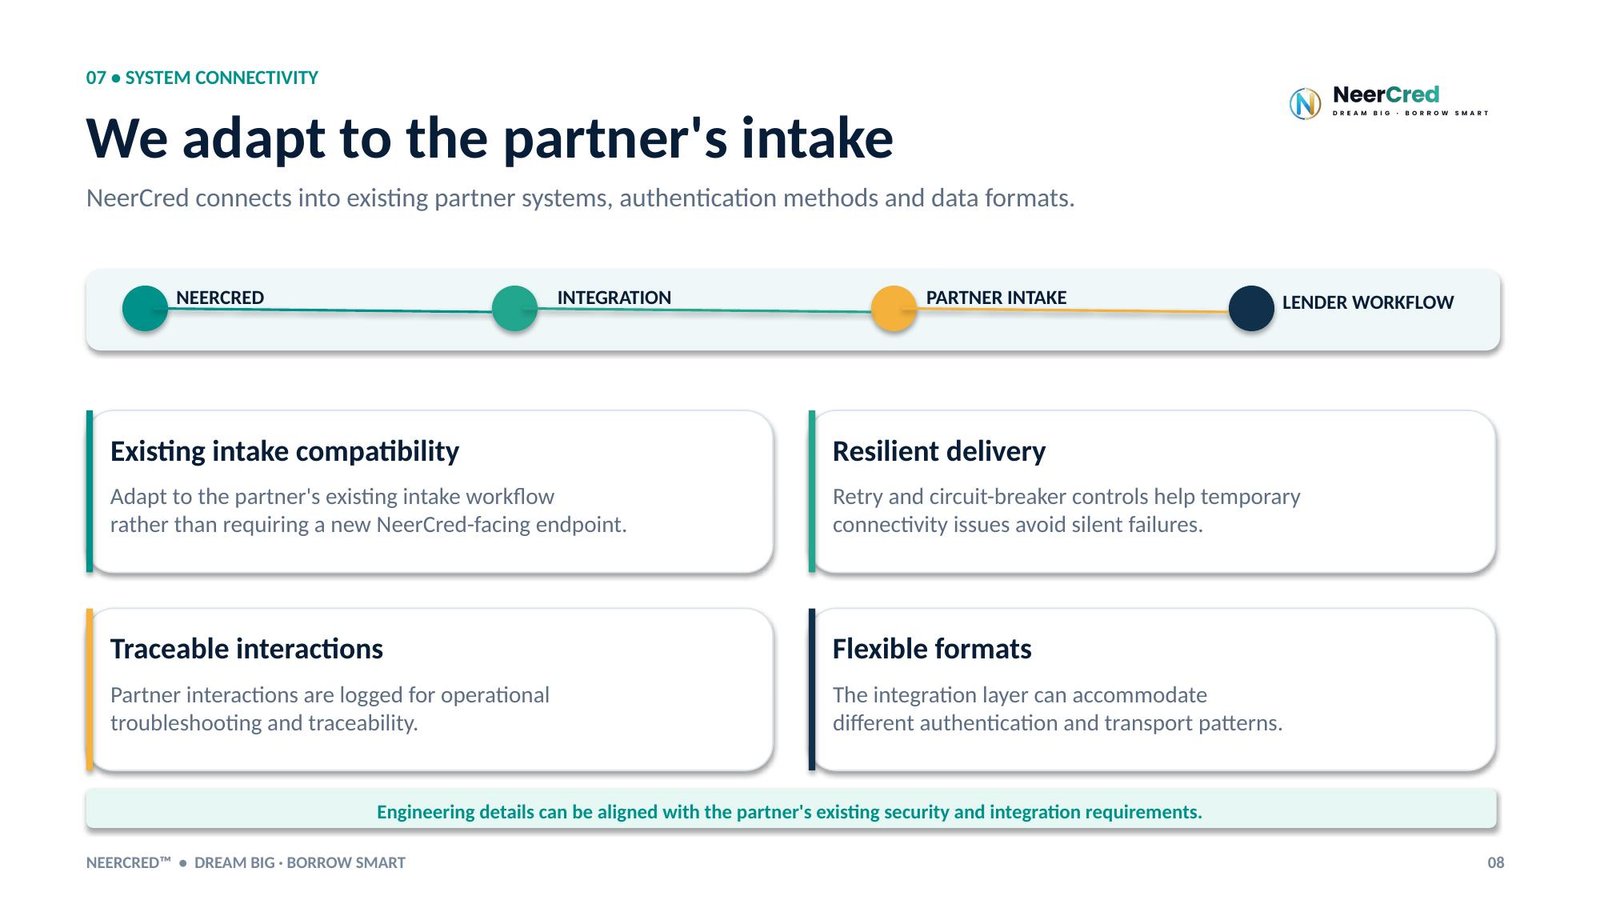
Onboarding a new lending partner is a configuration change on our side, not a rewrite — which is why we can adapt to your existing intake system instead of asking you to build something new to receive applicants. Every connection includes automatic retry handling so a temporary outage on either side doesn't silently drop applicants, and every interaction is logged for traceability and troubleshooting.
The full partner deck
Click through for the complete overview — delivery methods, integration model, and what a partnership with NeerCred looks like in practice.
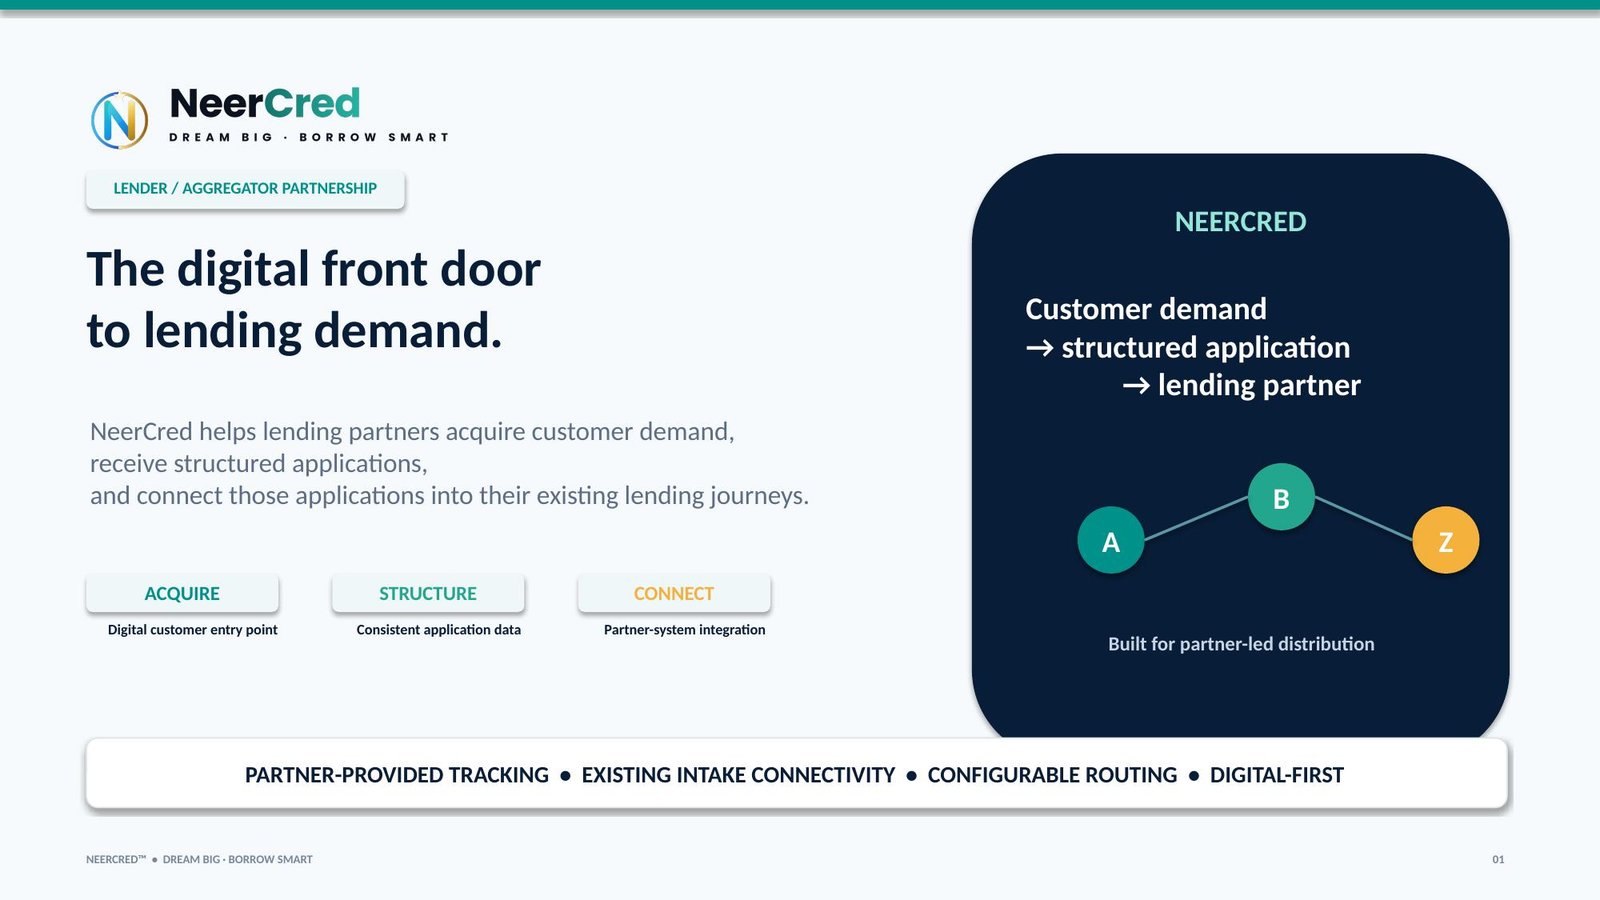
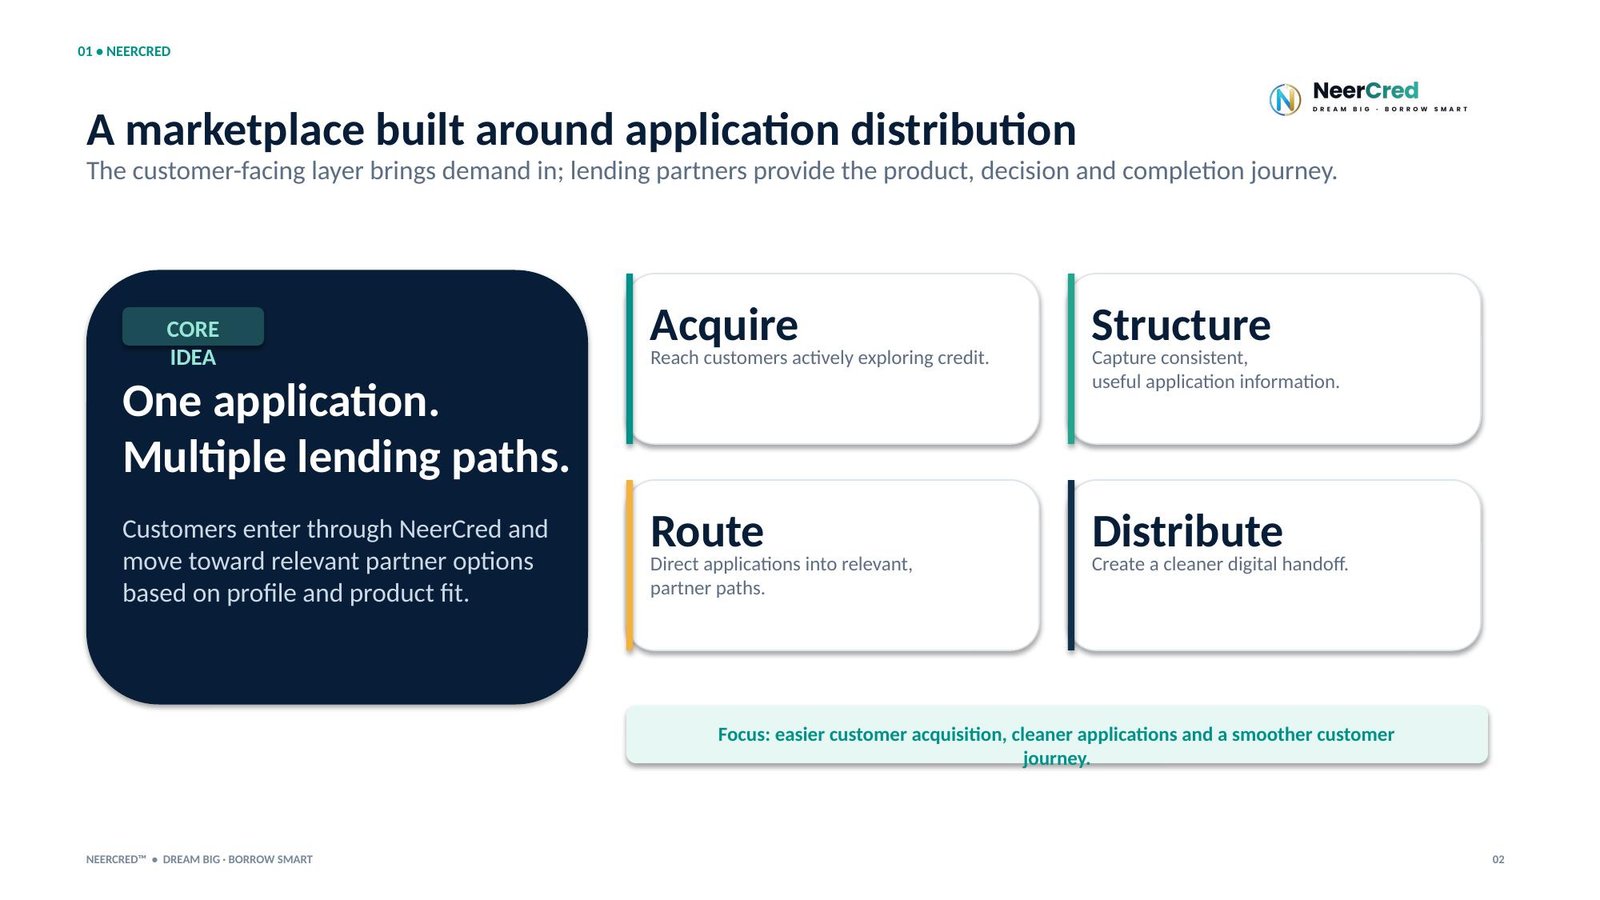
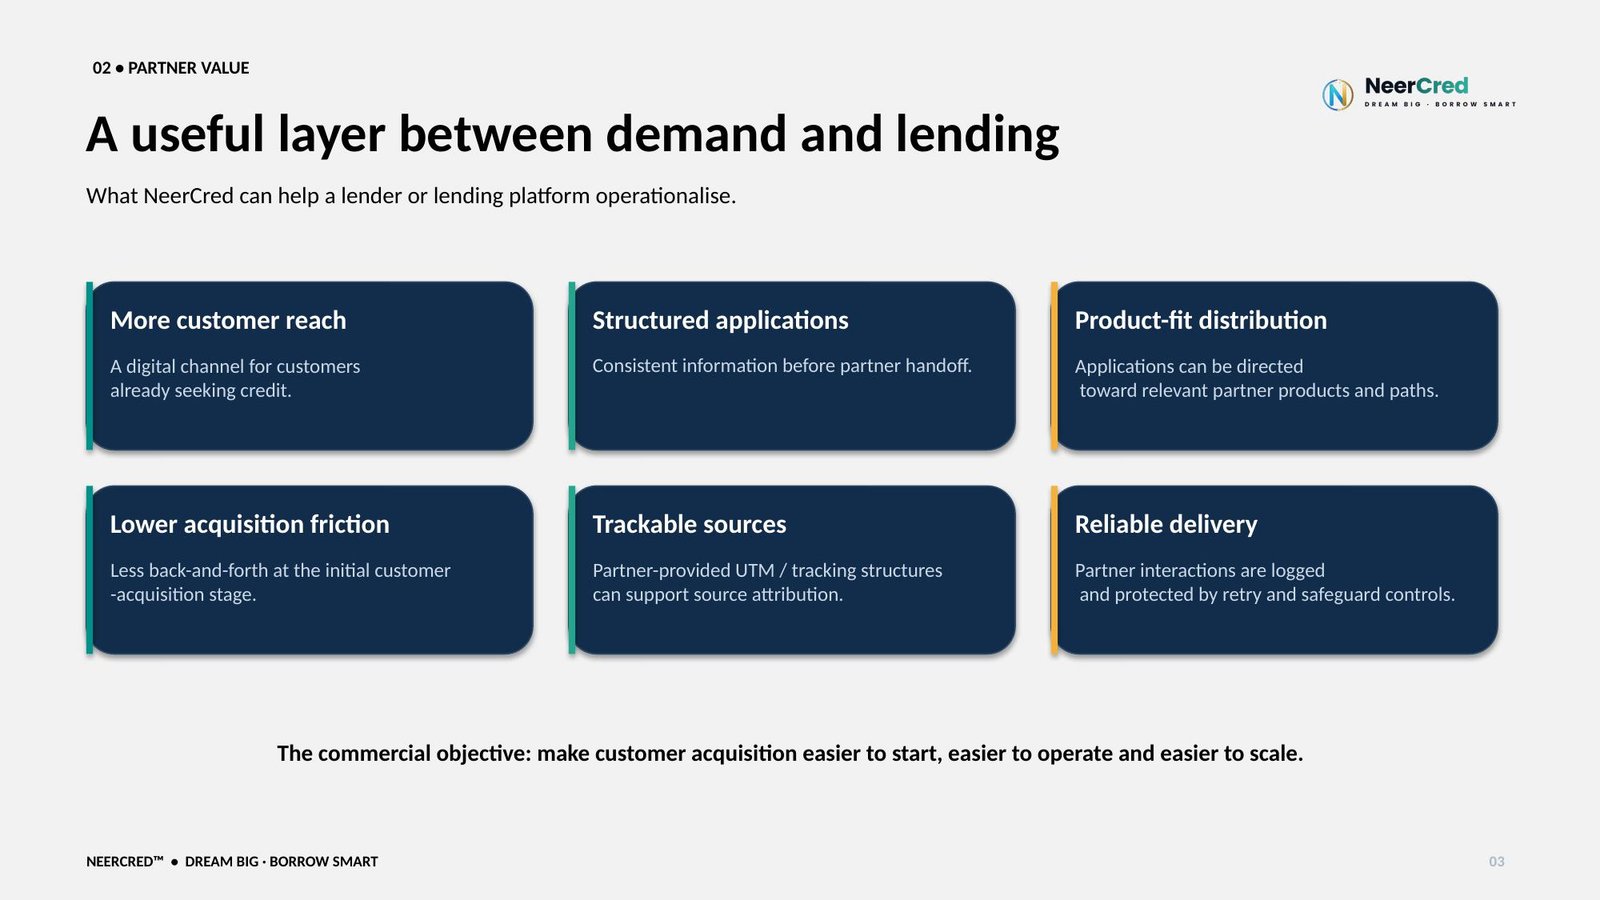
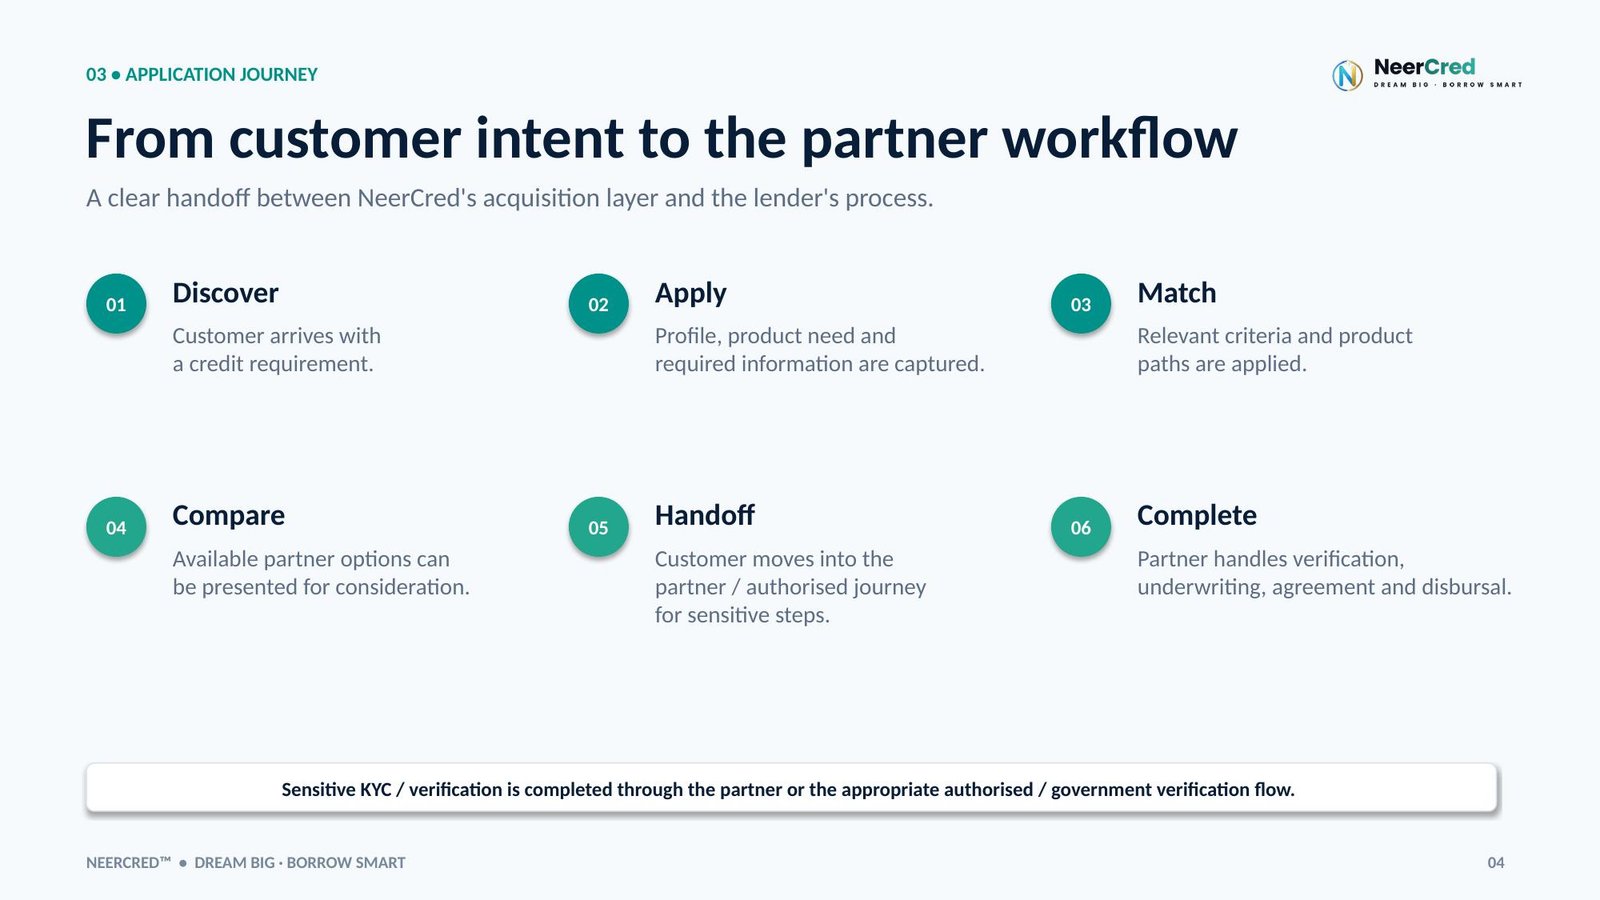
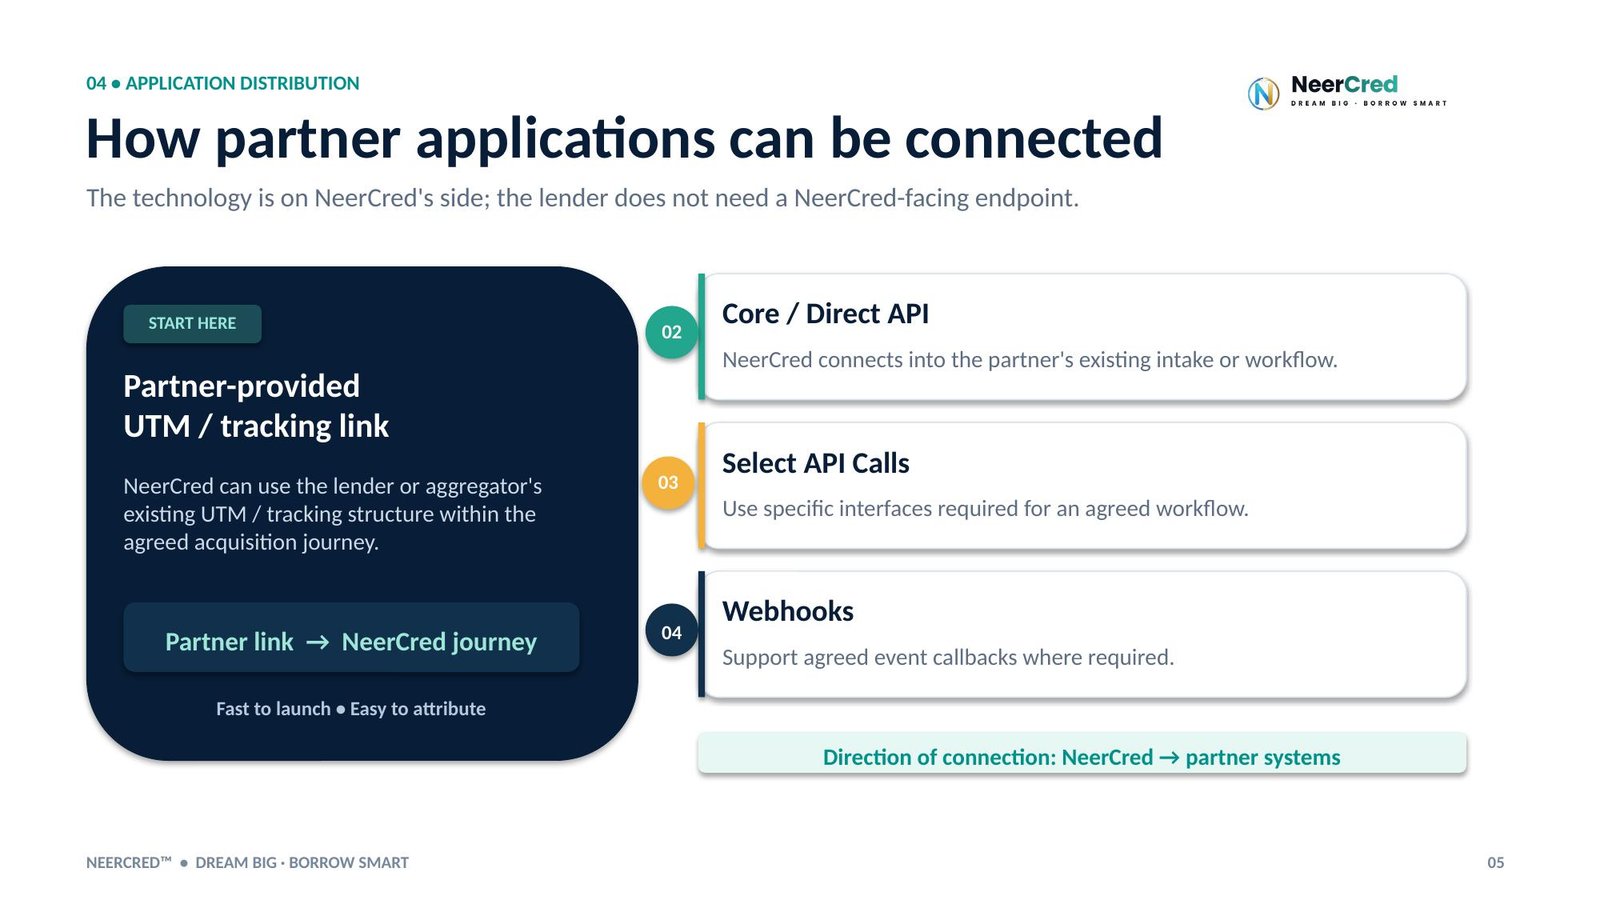
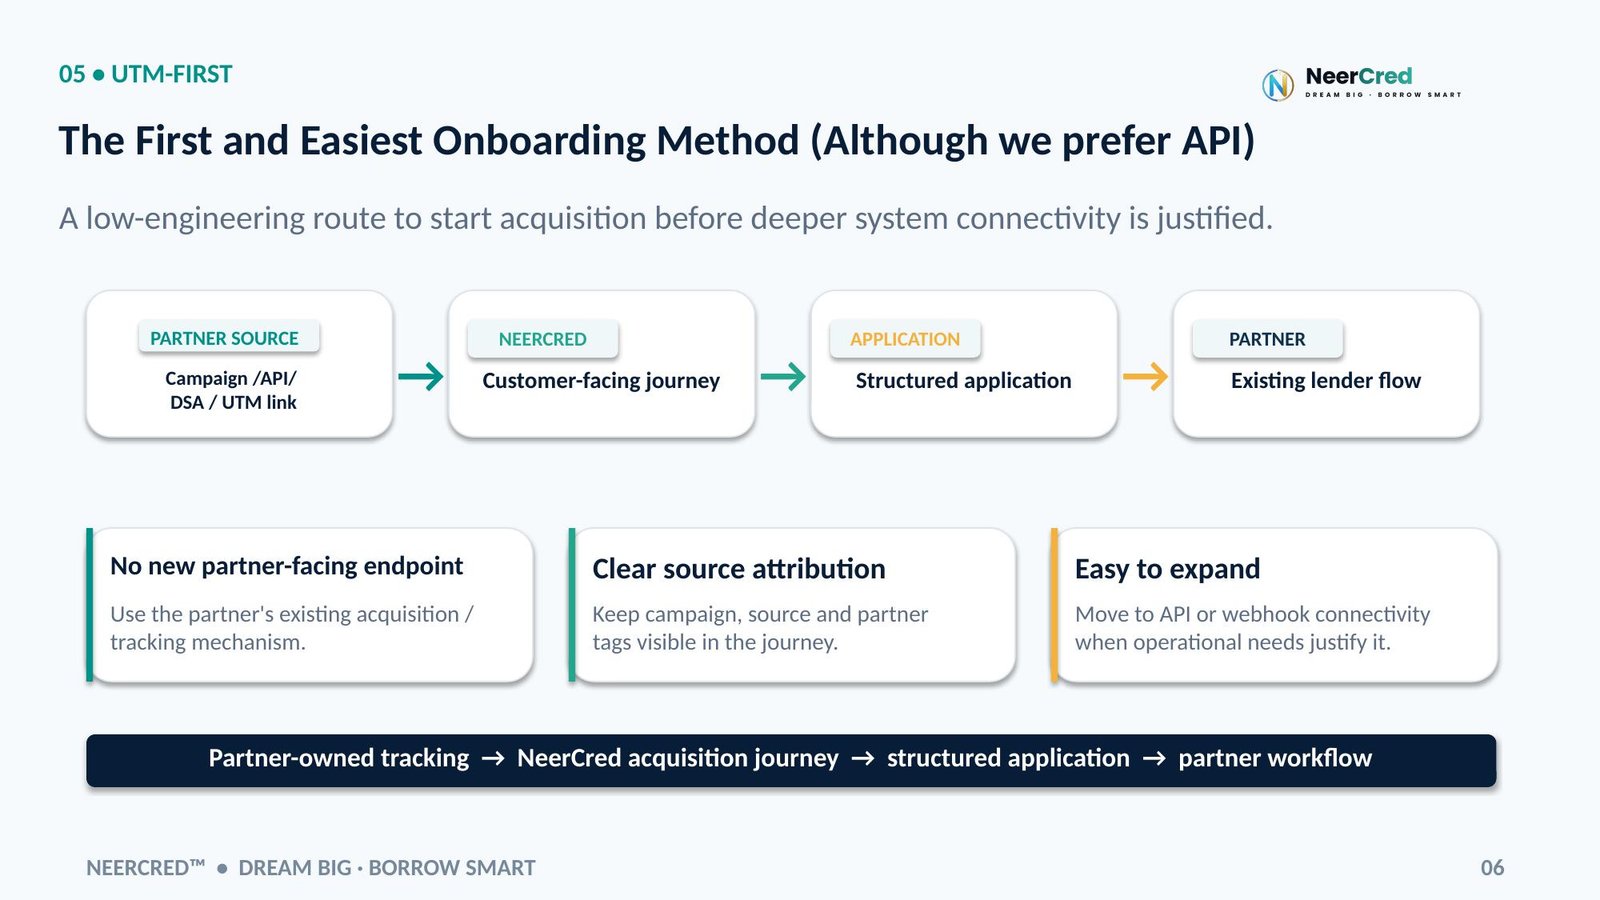
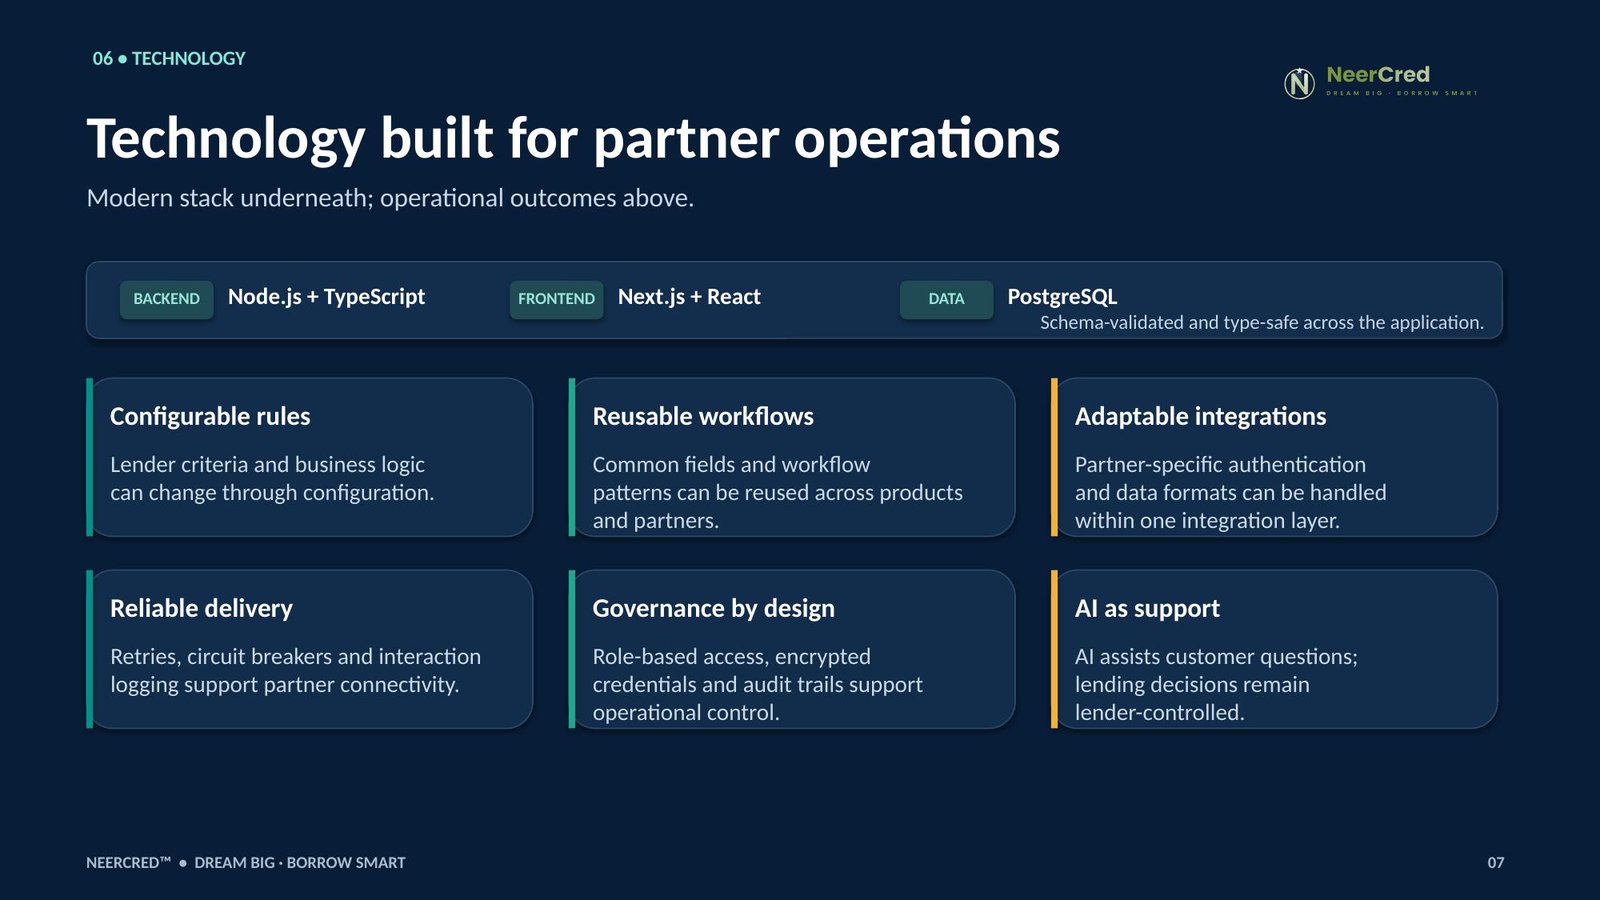
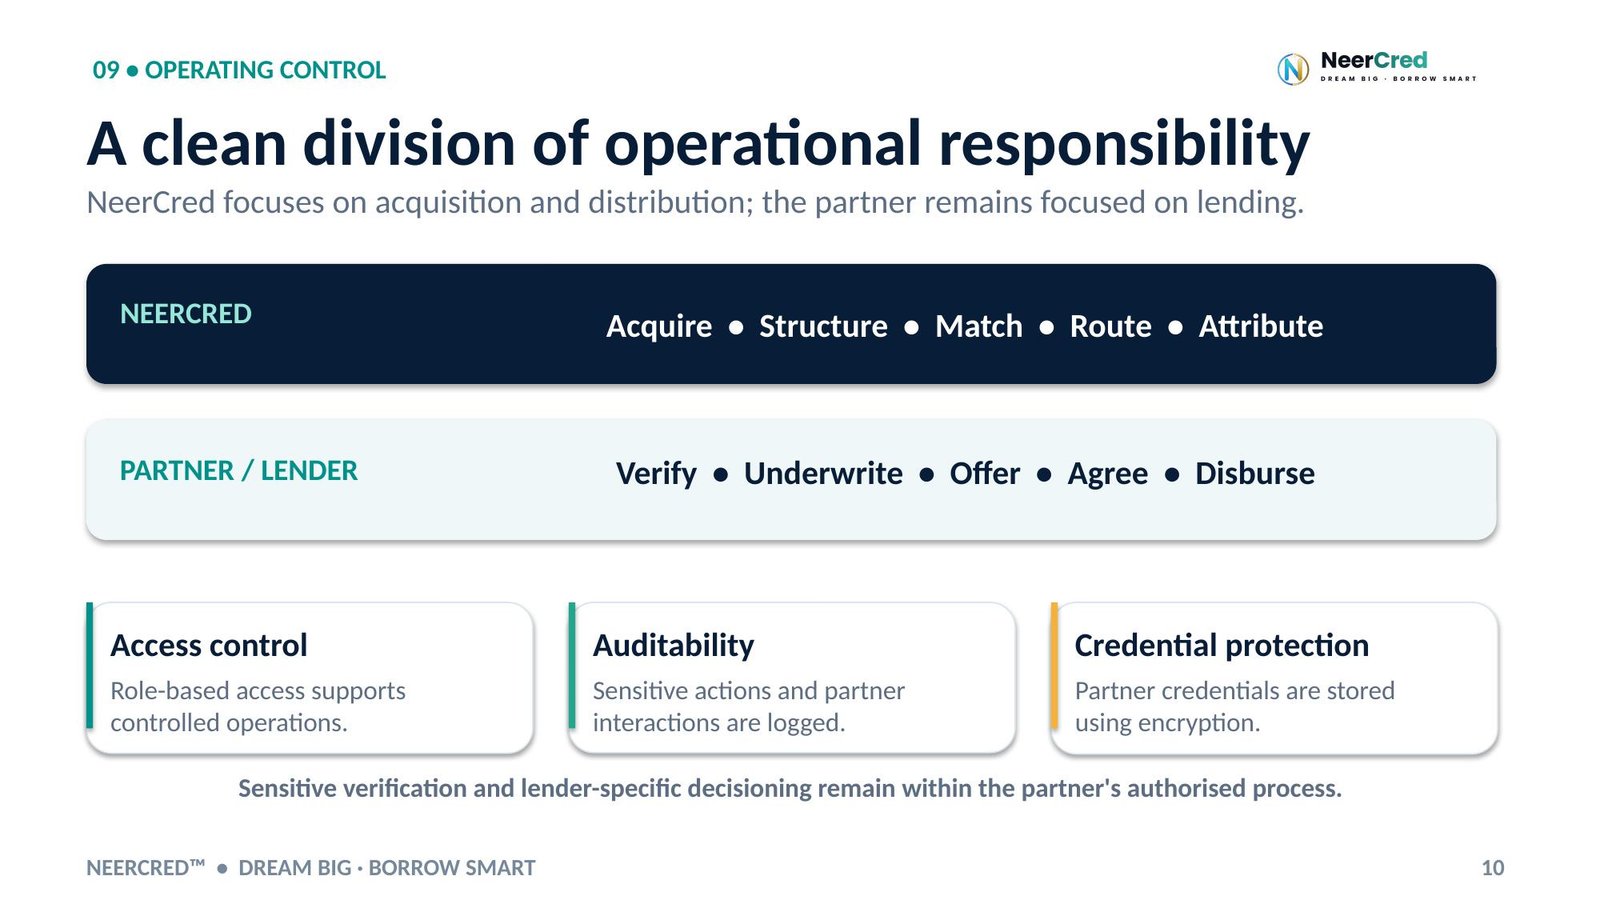
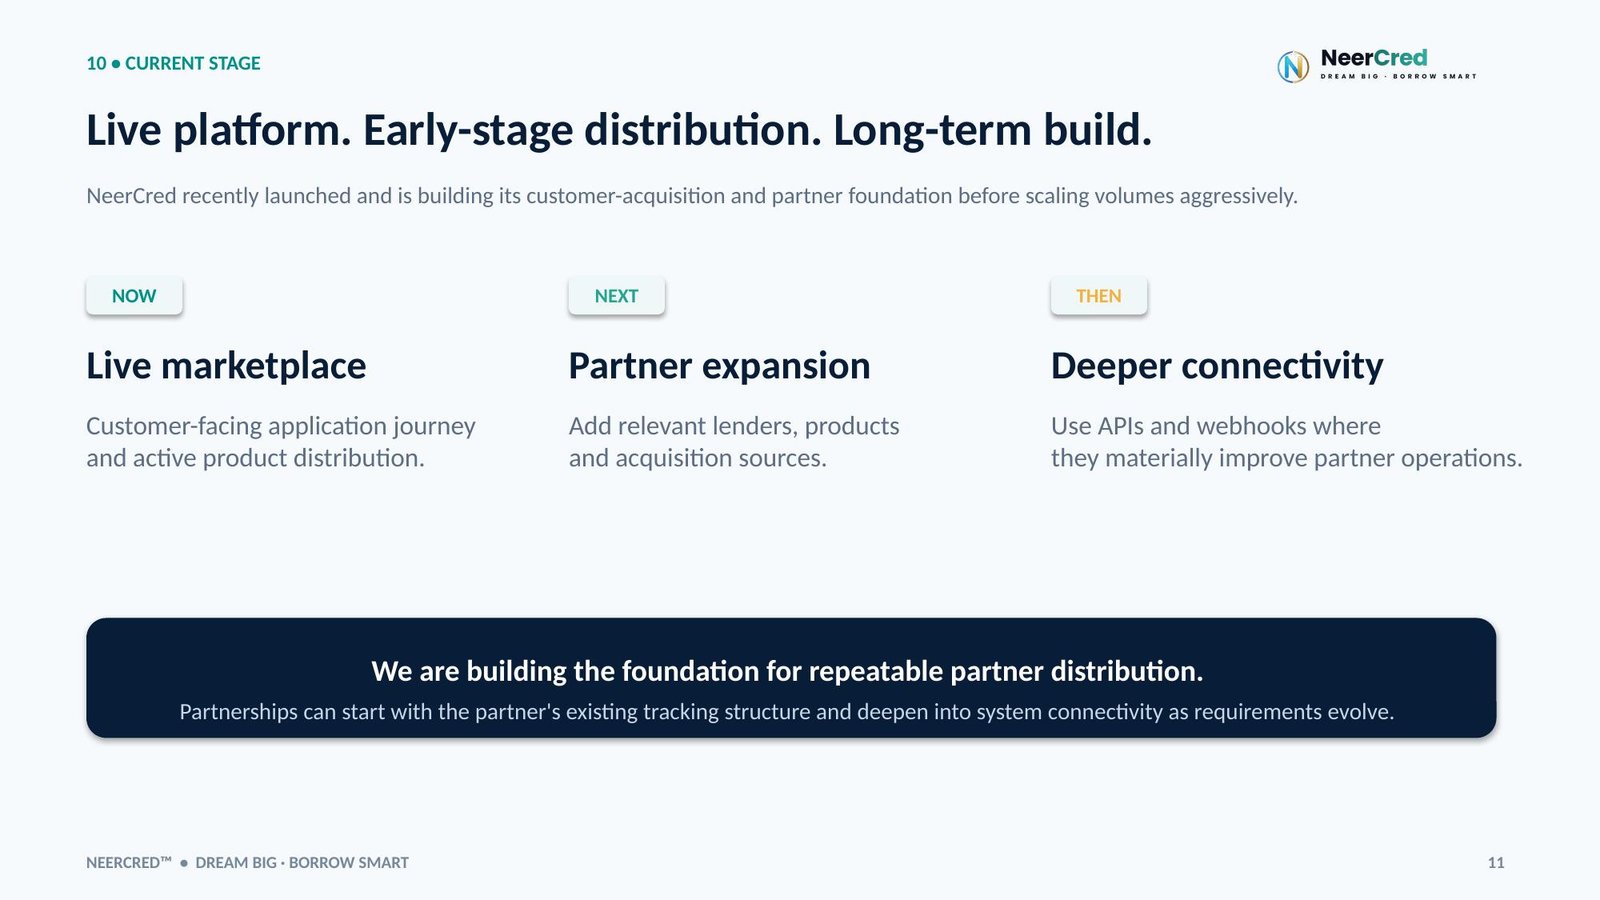
The digital front door to lending demand. NeerCred helps lending partners acquire customer demand, receive structured applications, and connect those applications into their existing lending journeys. Acquire: digital customer entry point. Structure: consistent application data. Connect: partner-system integration. Built for partner-led distribution — partner-provided tracking, existing intake connectivity, configurable routing, digital-first.A marketplace built around application distribution. The customer-facing layer brings demand in; lending partners provide the product, decision and completion journey. Acquire: reach customers actively exploring credit. Structure: capture consistent, useful application information. Route: customers enter through NeerCred and move toward relevant partner options based on profile and product fit. Distribute: direct applications into relevant partner paths, creating a cleaner digital handoff. Focus: easier customer acquisition, cleaner applications, and a smoother customer journey.A useful layer between demand and lending. What NeerCred can help a lender or lending platform operationalise. More customer reach: a digital channel for customers already seeking credit. Structured applications: consistent information before partner handoff. Product-fit distribution: applications can be directed toward relevant partner products and paths. Lower acquisition friction: less back-and-forth at the initial customer-acquisition stage. Trackable sources: partner-provided UTM/tracking structures can support source attribution. Reliable delivery: partner interactions are logged and protected by retry and safeguard controls. The commercial objective: make customer acquisition easier to start, easier to operate, and easier to scale.From customer intent to the partner workflow. A clear handoff between NeerCred's acquisition layer and the lender's process. 1. Discover: customer arrives with a credit requirement. 2. Apply: profile, product need and required information are captured. 3. Match: relevant criteria and product paths are applied. 4. Compare: available partner options can be presented for consideration. 5. Handoff: customer moves into the partner/authorised journey for sensitive steps. 6. Complete: partner handles verification, underwriting, agreement and disbursal. Sensitive KYC/verification is completed through the partner or the appropriate authorised/government verification flow.How partner applications can be connected. The technology is on NeerCred's side; the lender does not need a NeerCred-facing endpoint. Core/Direct API: NeerCred connects into the partner's existing intake or workflow. Partner-provided UTM/tracking link: NeerCred can use the lender or aggregator's existing UTM/tracking structure within the agreed acquisition journey. Select API calls: use specific interfaces required for an agreed workflow. Webhooks: support agreed event callbacks where required. Fast to launch, easy to attribute. Direction of connection: NeerCred to partner systems.UTM-first: the first and easiest onboarding method. Although NeerCred prefers API, UTM-first is a low-engineering route to start acquisition before deeper system connectivity is justified. Flow: partner source, to NeerCred application, to partner. No new partner-facing endpoint: uses the partner's existing acquisition/tracking mechanism. Clear source attribution: keeps campaign, source and partner tags visible in the journey. Easy to expand: move to API or webhook connectivity when operational needs justify it.Technology built for partner operations. A modern stack underneath, with operational outcomes above. Backend: Node.js and TypeScript. Frontend: Next.js and React. Data: PostgreSQL, schema-validated and type-safe across the application. Configurable rules: lender criteria and business logic can change through configuration. Reusable workflows: common fields and workflow patterns can be reused across products and partners. Adaptable integrations: partner-specific authentication and data formats can be handled within one integration layer. Reliable delivery: retries, circuit breakers and interaction logging support partner connectivity. Governance by design: role-based access, encrypted credentials and audit trails support operational control. AI as support: AI assists customer questions; lending decisions remain lender-controlled.We adapt to the partner's intake. NeerCred connects into existing partner systems, authentication methods and data formats. Existing intake compatibility: adapts to the partner's existing intake workflow rather than requiring a new NeerCred-facing endpoint. Resilient delivery: retry and circuit-breaker controls help temporary connectivity issues avoid silent failures. Traceable interactions: partner interactions are logged for operational troubleshooting and traceability. Flexible formats: the integration layer can accommodate different authentication and transport patterns. Engineering details can be aligned with the partner's existing security and integration requirements.Structured applicants, not just raw leads. The customer journey is designed to collect, pre-screen and format information before partner handoff. Pre-screened: relevant eligibility criteria can be applied before partner handoff. Deduplicated: duplicate applications can be identified before creating avoidable partner-side work. Application snapshot includes contact details, product and requested amount, requested tenure, computed EMI, criteria-based eligibility, and partner/tracking source attribution — consistent fields and calculated values, so the partner receives predictable, structured data. Practical outcome: less interpretation work between customer intent and the partner queue.A clean division of operational responsibility. NeerCred focuses on acquisition and distribution; the partner remains focused on lending. NeerCred: acquire, structure, match, route, attribute. Partner/lender: verify, underwrite, offer, agree, disburse. Access control: role-based access supports controlled operations. Auditability: sensitive actions and partner interactions are logged. Credential protection: partner credentials are stored using encryption. Sensitive verification and lender-specific decisioning remain within the partner's authorised process.Live platform. Early-stage distribution. Long-term build.. NeerCred recently launched and is building its customer-acquisition and partner foundation before scaling volumes aggressively. Now: live marketplace — customer-facing application journey and active product distribution. Next: partner expansion — add relevant lenders, products and acquisition sources. Then: deeper connectivity — use APIs and webhooks where they materially improve partner operations. Partnerships can start with the partner's existing tracking structure and deepen into system connectivity as requirements evolve.Let's make customer acquisition simpler. Customer, to application, to lending partner. For banks, NBFCs and lending platforms looking to add a digital acquisition path, NeerCred can provide a structured route from customer demand to partner workflow. Partnership queries: partnership@neercred.com — www.neercred.com.
1 / 12
NeerCred does not sell or issue loans on its own and does not charge applicants any fee. We work only with RBI-regulated banks and NBFCs, and loan sanction always remains at the sole discretion of the partner bank or NBFC. See our compliance page for details.
Frequently asked questions
How does NeerCred deliver applicants to lending partners?
Through whichever method fits your systems: a partner dashboard, mediated routing through an existing aggregator relationship, or a direct push into your own intake system.
Does our team need to build anything to receive applicants from NeerCred?
No. For a direct integration, NeerCred calls into your existing intake system using the authentication and format it already expects, rather than asking you to build something new to reach us.
What applicant data do we receive?
Structured, consistent data — verified contact details, requested amount and tenure, computed EMI — rather than a raw form submission. Applicants are checked against your eligibility criteria and deduplicated before delivery.
Does NeerCred work with unregulated lenders?
No. We work only with RBI-regulated banks and NBFCs.
Looking to source applicants instead?
If you're a DSA, connector, or lead-generation partner rather than a lending institution, NeerCred partners on the sourcing side too.